Rear-Ended at a Light? Three Facts Decide Whether You Need Counsel at All
Contingency fees, state no-fault rules and injury thresholds decide whether a crash claim is a phone call or a case. A worked example of where the line actually falls.
| Author | Junko Halloran |
|---|---|
| Section | Law & Legal |
| Published | |
| Length | 1,167 words · 5 min |
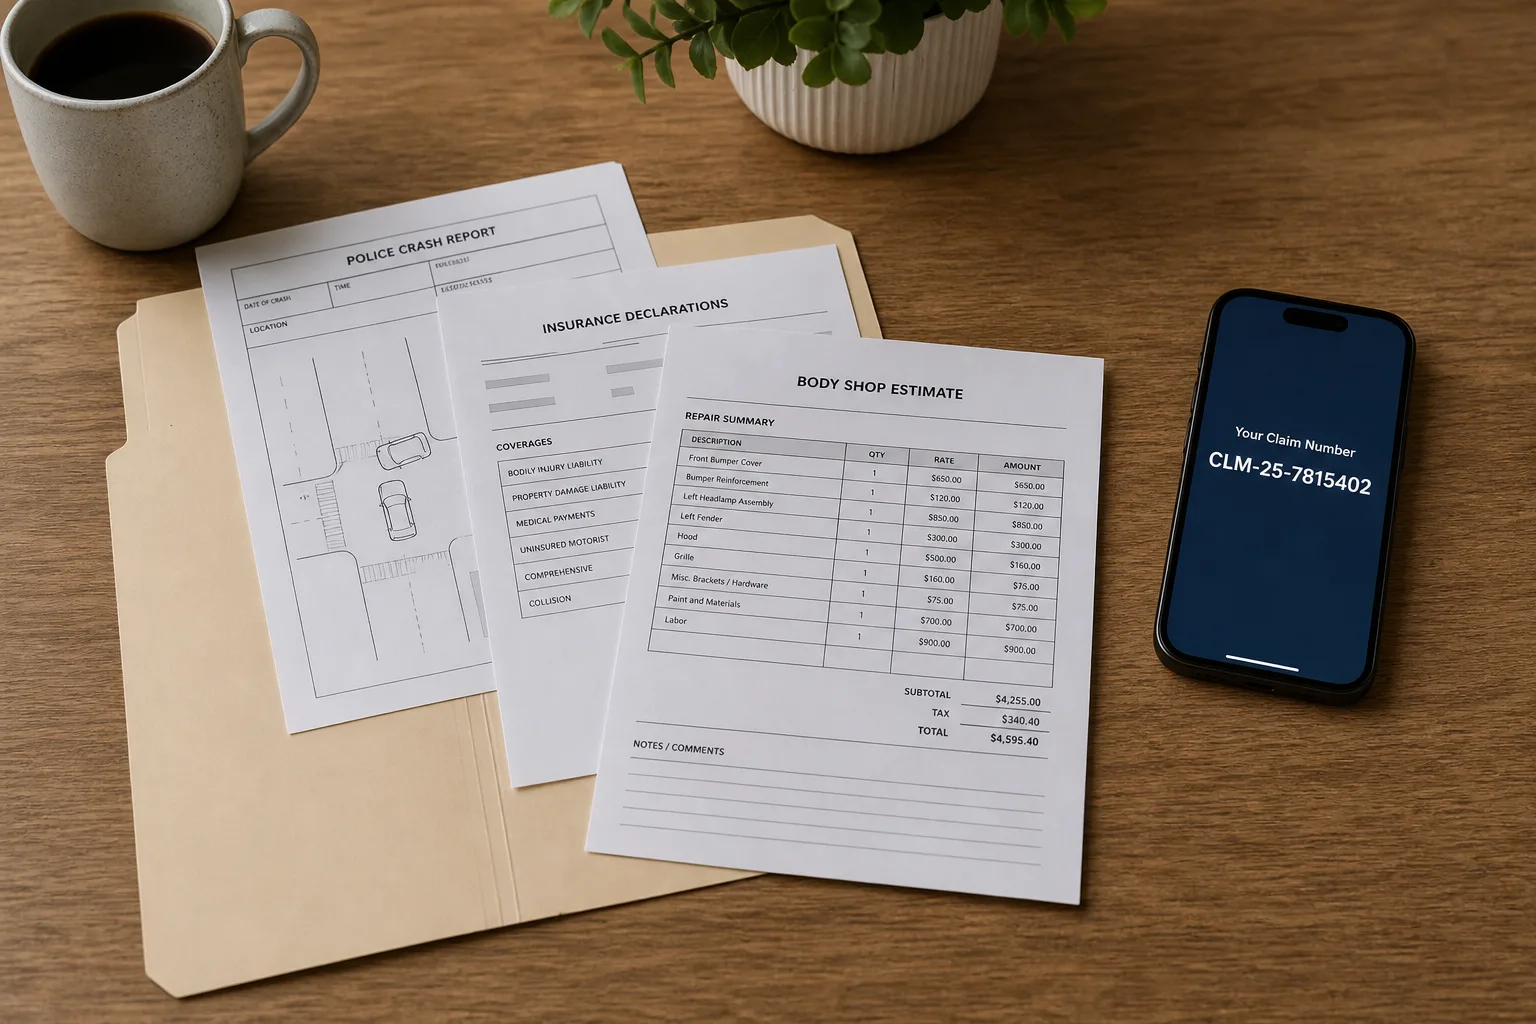
A household that gets rear-ended at a stoplight on Tuesday usually has the insurer's claim number by Wednesday and an adjuster's call by Thursday. Somewhere in that window, a relative will say you should talk to a lawyer, and someone else will say lawyers take a third and you would have been better off alone. Both pieces of advice are given with equal confidence and neither one is a rule. Whether a crash claim needs counsel turns on three facts: what state you were in, whether anyone was hurt in a way that still hurts in six weeks, and whether fault is actually being contested. Everything else is noise, and the reason those three facts matter has a traceable history.
Why an ordinary household can hire anyone at all
For most of American legal history, hiring a lawyer meant paying one by the hour, which meant that a person with a broken wrist and no savings had no practical access to the civil courts. The contingency fee changed that arithmetic. Under a contingency arrangement, the attorney is paid a percentage of what is recovered and nothing if nothing is recovered, which moves the risk off the household and onto the firm. English courts long treated such arrangements as improper; American courts, facing a population of people who could not otherwise sue anyone, did not. By the twentieth century contingency fees were standard in personal injury work and were written into state bar rules rather than tolerated at their edges.
The second change was visibility. Until the Supreme Court's 1977 decision in Bates v. State Bar of Arizona, state bars broadly prohibited attorneys from advertising, which meant that finding one was a matter of who your family already knew. After that decision the billboards appeared, and with them a genuine shift: a household with no professional contacts could find representation in an afternoon. The downside is that the volume of advertising now implies every crash needs a lawyer, which is not true, and the practical skill a household needs is reading its own situation before it dials anyone.
Your state already decided part of this for you
In the 1970s a number of states adopted no-fault auto insurance, under which your own policy pays your initial medical bills and lost wages through personal injury protection regardless of who caused the crash. The trade was that you give up the right to sue the other driver for pain and suffering unless your injury clears a threshold: either a dollar amount of medical expense or a verbal description such as a fracture, permanent disfigurement or significant limitation of a body function. Other states kept the traditional at-fault system, where the other driver's liability insurer pays and nothing bars you from claiming.
This is why advice does not travel. A neighbor who moved from a no-fault state and remembers his claim going nowhere is describing a threshold he did not clear, not a general truth about crashes. The practical step is to find out, before you make any decision, whether your state is no-fault, what the threshold is, and what your own policy's personal injury protection limit is. That last number is on your declarations page and it is typically the first money that moves. The National Highway Traffic Safety Administration is responsible for federal vehicle safety standards and crash reporting, but the rules that decide what your claim is worth are written state by state.
The worked example
Take three versions of the same stoplight collision, with illustrative numbers.
Version one. Bumper, trunk latch and a sensor: a body shop estimate of $3,800. Nobody saw a doctor. The other driver's insurer accepts fault within a week because its own insured admitted it. There is no injury claim, so there is no contingency fee to pay out of, and no attorney will take the file on contingency anyway. Hiring one hourly to argue over a $3,800 repair costs more than the gap you are arguing about. This claim is a phone call, a rental car authorization and three photographs.
Version two. Same impact, but you have neck pain that is still there at week six, two months of physical therapy at a few hundred dollars a visit, and four missed shifts. Now there are medical bills, a wage loss, and a health insurer that will assert a lien or subrogation interest against anything you collect. The adjuster offers a number early, before treatment ends. This is the situation where a car accident lawyer earns the fee, because the value of an injury claim cannot be known until the treatment has concluded and the lien has been negotiated down, and almost nobody handling their own file knows that the lien is negotiable.
Version three. The other driver tells the insurer you ran the light. Now fault is contested, there may be a comparative negligence reduction applied to whatever you recover, and the file needs the intersection camera footage pulled before it is overwritten, typically within days or weeks. Get counsel immediately. The evidence has an expiration date that nobody will remind you about.
On fee math: a typical personal injury contingency is a third of the gross recovery if the case settles before suit is filed and higher, often 40 percent, if suit is filed, plus case costs such as medical record fees and filing fees deducted separately. So a $30,000 settlement at one third leaves $20,000 before costs and liens. The honest question is not whether a third is a lot. It is whether the represented outcome, after the fee and after the lien reduction, beats the number the adjuster would have handed you unrepresented. For version one that is clearly no. For version two it is frequently yes, and the gap cannot be stated as a percentage in advance because it depends on the lien, the policy limits and the treatment record.
The clock nobody sends you a reminder about
Every state sets a statute of limitations for personal injury claims, commonly two or three years from the crash date but shorter in some states and much shorter when a government vehicle is involved, where a formal notice of claim may be due within months. Your insurer also has contract deadlines for notice and for cooperation, which sit in the policy rather than in state law. Write both dates on the front of the folder the day you open it. A free consultation, which most injury firms offer, is the cheapest way to confirm which clock applies to you, and a consultation is not a retainer.
The useful habit is to treat the first two weeks as fact-gathering rather than decision-making: the police report number, the declarations page, the photographs, the names of every provider you have seen. If the file stays small, you close it yourself and keep the whole check. If it does not, you walk into a consultation with the documents already in order, which is the version of that meeting that produces an actual plan.
About the author
Junko covers what work costs and why two quotes for the same job differ.